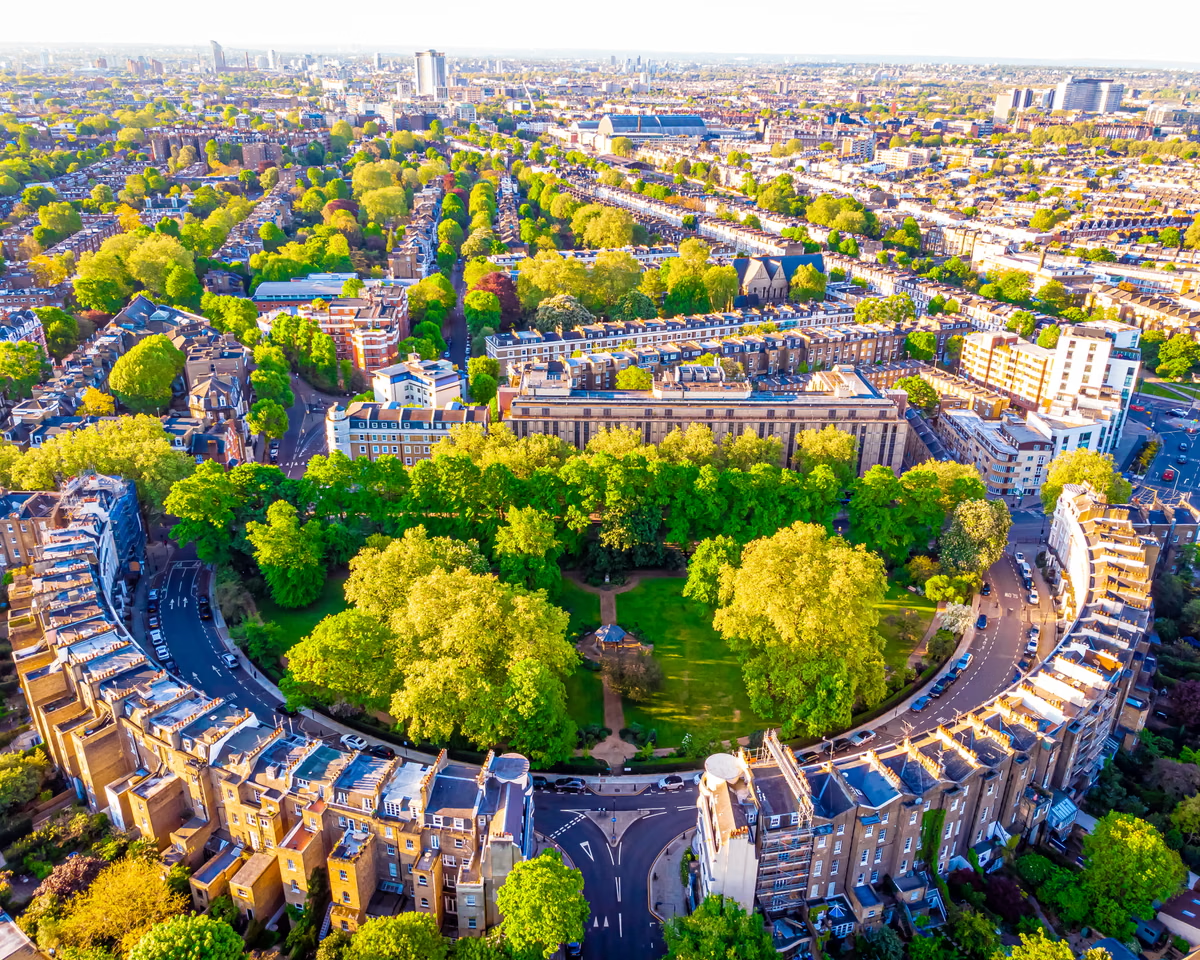
London’s luxury property sector is experiencing a significant slowdown, with newly built flats in the capital’s most prestigious neighbourhoods—including Mayfair, Chelsea, and Kensington—frequently remaining unoccupied. These properties, often marketed with amenities like concierge services and marble-finished lobbies, are failing to attract sufficient buyers, leaving developers with a mounting surplus of high-end assets. Leaving brand-new properties in London’s most desirable postcodes standing empty, the problem for property developers is finding wealthy residents to fill them. While a range of factors have put a squeeze on some wealthy buyers, the multimillion-pound homes developers are building remain way out of reach for the average Londoner. Which was hit hard by Brexit, the Covid pandemic and higher property taxes after a period of rapid price growth post-financial crisis, a rise in borrowing costs has become the latest headache in the high-end property market. After its owners ran out of funding, it appointed administrators in August. The market is slow, even on the most expensive roads in the country. The shaky market is starting to hit jobs. And rates can change even after the point of exchange, if you are relying on a mortgage … it is really difficult. However, a buoyant rental market does not represent a lifeline. “When rents are up, but the house prices are sticky and land prices are still, it takes time for them to adjust,” Neale said, for developers. “Everyone is confident about London in the long term because we have this huge shortage of housing.
Market researcher Molior reports that by the end of September, Zone 1 of London, encompassing the City, the West End, and prime areas such as Marylebone and Mayfair, held 1,400 completed but unsold homes. This figure represents a threefold increase compared to 2016. Furthermore, development activity has plummeted, with only 1,600 homes breaking ground in the region over the past year, marking a 75% decline from a decade ago. Just 1,600 homes started construction in the area in the past 12 months, 75% fewer than a decade ago, it found.
For developers, the commercial viability of luxury projects is increasingly compromised by volatile construction costs and the high expense of borrowing. The combination of rising overheads and a sluggish sales environment has pushed some firms into insolvency. London Richmond, a specialist developer with a portfolio of 20 properties in affluent areas like South Kensington and Wimbledon, entered administration in August. The firm’s administrator, BTG, confirmed that over 300 creditors are awaiting payment of £39m in outstanding debt. Borrowing is now more expensive and financing a project can mean sitting on a fast-growing debt pile before a single flat is sold, construction costs are rising and volatile.
Ardmore Construction, a significant player involved in major projects across King’s Cross, Mayfair, and Kensington, also collapsed into administration in 2025. Although its parent organization, Ardmore Group, continues to operate following a creditor-approved voluntary arrangement, its construction arm reported owing more than £29m to subcontractors and creditors as of September. Other industry leaders are scaling back; Berkeley Group has ceased land acquisition, Taylor Wimpey intends to exit the London market, and British Land has suspended the second phase of its Canada Water project due to cost pressures and lacklustre demand. The developer Ardmore Construction – which was building 10 major projects across the capital including two residential towers in King’s Cross and luxury hotel developments in Mayfair and Kensington – also fell into administration, in 2025. A luxury residential development a stone’s throw away from Buckingham Palace, entered administration in 2023, no 1 Palace Street. Administrators at FRP for No 1 Palace Street declined to comment.
According to Jon Neale of Montagu Evans, developers are trapped between ballooning construction expenses and weakening appetite from buyers. Changes to stamp duty—which can reach 19% for additional properties—and the abolition of the non-dom tax regime have particularly deterred overseas investors. Marcus Dixon of JLL notes that uncertainty regarding holding costs and taxation has discouraged discretionary purchasers, noting that the market is struggling because it lacks the support of needs-based buyers. For example, the purchase of a £10m home could trigger a £1.9m stamp duty bill, overseas buyers can face stamp duty of up to 19% on additional properties – which means.
The stagnation is reflected in broader economic metrics. Official figures from the Office for National Statistics indicate that construction vacancies dropped by 7,000 during the third quarter, making it one of the hardest-hit sectors in the UK workforce. Meanwhile, average flat prices, which stood at approximately £431,000 in June, have failed to track with inflation; had they matched general trends, they would be roughly £180,000 higher today. The average flat price was about £431,000 in June, down £2,000 from the same month in 2016, according to Land Registry figures published in August.
As high-net-worth individuals, defined as those with at least $30m in investable assets, pull back, many are opting to rent rather than purchase. According to jerome Lartaud, a buying agent for ultra high net worth people – typically defined as those with at least $30m (£22.4m) in investable assets –, Many were now choosing to rent rather than buy. It is a lot of pressure for people with mortgages.”.
Buying agent Jerome Lartaud observes that both domestic and international buyers are placing acquisitions on hold, preferring to reside in rentals.
Data from JLL supports this trend, showing a record 338 luxury homes with annual rents exceeding £150,000 leased in the past year, a 14% year-on-year increase.
However, industry experts warn that this shift toward rentals is an insufficient remedy for developers, as the price gap between stagnant asset values and elevated land costs remains difficult to bridge.