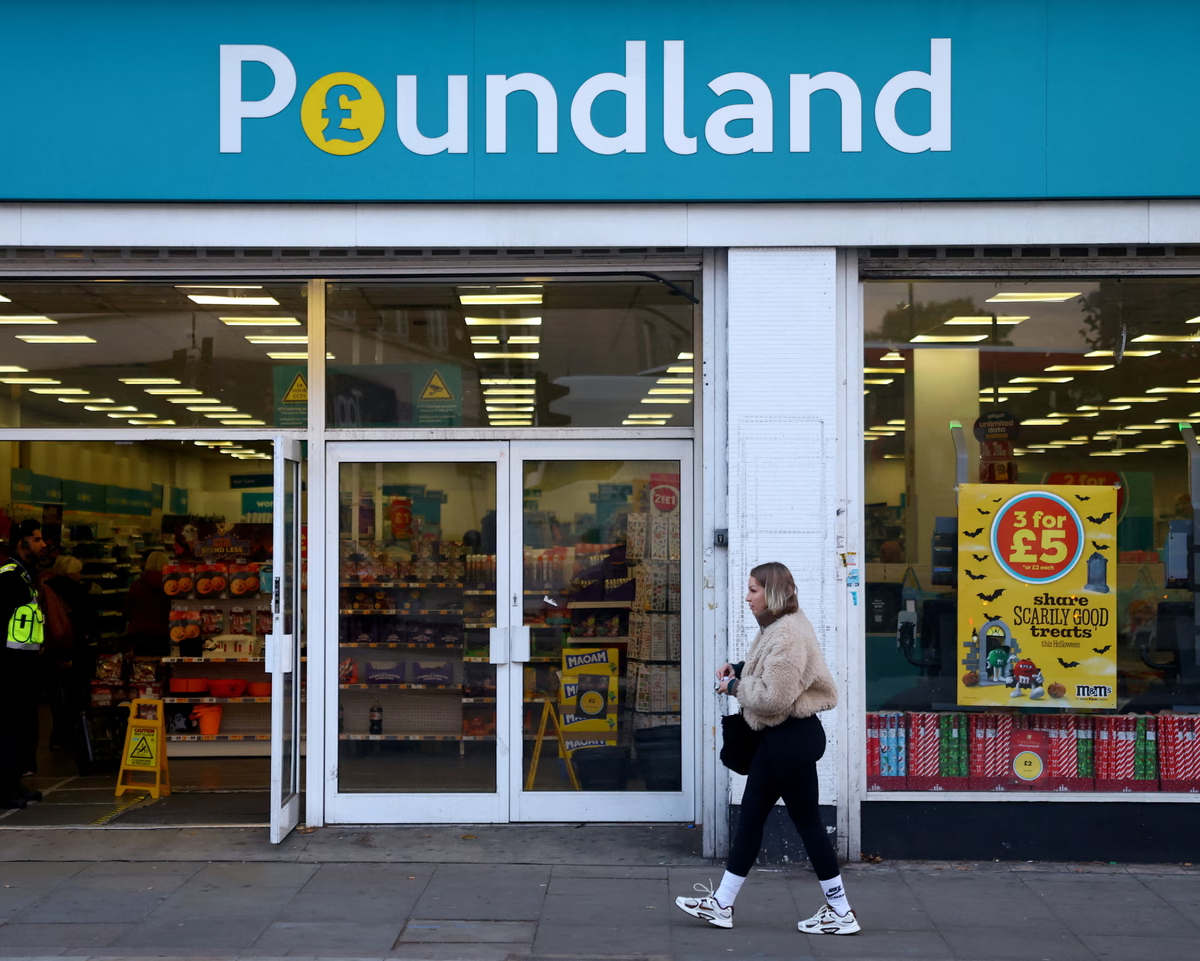
Lawmakers have launched a sharp critique against the owner of Poundland, alleging that millions of pounds were extracted from the retailer while it teetered on a “knife-edge.” The accusations arise as the budget chain, which supports 12,000 jobs across 600 locations in the UK and Ireland, prepares to head to the high court on Thursday morning to request an extension of its legal protection from creditors. Poundland filed a notice of intention to appoint administrators two weeks ago.
Poundland’s management is seeking an additional 10 working days of breathing room. This request follows an injection of £10 million in funds by the owner, Gordon Brothers, which is reportedly supporting the extension to allow the business to maintain stock levels and keep trading. If the court denies the grace period, the company risks being forced into administration, with advisor Alix Partners already standing by. Led by Barry Williams, who had been fighting to save the business, the committee separately heard from Poundland’s management team.
The controversy intensified after Mark Newton-Jones, the European head of Gordon Brothers, provided two hours of private testimony to the Commons business select committee on Wednesday.
The committee’s chair, Liam Byrne, expressed deep concern that the firm’s actions have jeopardized thousands of high-street jobs.
Byrne noted that despite the business operating on a “knife-edge” over the past 17 months, millions were removed, potentially strangling the retailer of necessary liquidity during its critical pre-Christmas trading window. They have taken millions out of Poundland when the business was on a ‘knife-edge’. “Now Poundland appears to be on the rebound, there’s concerning signs it’s been strangled of access to its own funds in what should be its busiest trading period in the run-up to Christmas. “Worse, Gordon Brothers refused to say it will prioritise saving jobs over and above its own financial returns.”, he said: “Over the last 17 months. According to sources, Poundland continued to trade well, with sales up year on year, despite its problems, but it has only enough cash to support the business for a short period.
Byrne further criticized the owners for failing to provide assurances that saving jobs would be prioritized over financial returns. Currently, Poundland continues to show year-on-year sales growth, though its cash reserves remain tight. Gordon Brothers maintains that the chain remains vulnerable to market downturns.
The ownership situation is complicated by the company’s history; Gordon Brothers acquired Poundland for a nominal £1 from the European retail group Pepco in June 2025. Today, £7.5 million of the £30 million in outstanding shareholder debt is still held by Pepco, which has signaled a willingness to wait for repayment to help preserve the chain.
Discussions regarding a potential sale are ongoing, with Gordon Brothers considering three different bidders. However, the firm has indicated that a break-up of the retailer—selling off individual stores and inventory—might generate more revenue than a full sale. Current bids are reportedly lower than the £30 million in debt attached to the company.
Among the interested parties is the Martin Property Group, a Northern Irish family firm that is backing a management-led rescue effort. Their initial offer was dismissed by Gordon Brothers for being insufficient, covering less than half of the £30 million target with an upfront payment of under £7 million. Another contender, the Xyra Group, has reportedly proposed an offer of approximately £30 million total, including £12 million in cash upfront, though the firm lacks prior experience in the retail sector. A little-known finance company, Xyra Group, is thought to have offered about £12m up front and close to £30m in total. However, Xyra has not been involved with retail businesses previously.